
Access both platforms from your single Saxo account.

Nvidia after the sell-off: three ways to use options around earnings
Summary: Nvidia has fallen twice in a week and reports on 17 November 2026. This article compares three ways to use options around the report: selling a put before it, selling one after it, or buying a put spread, each with its risk set out.
What can options do for an investor who likes Nvidia but cannot know which way the shares go next?
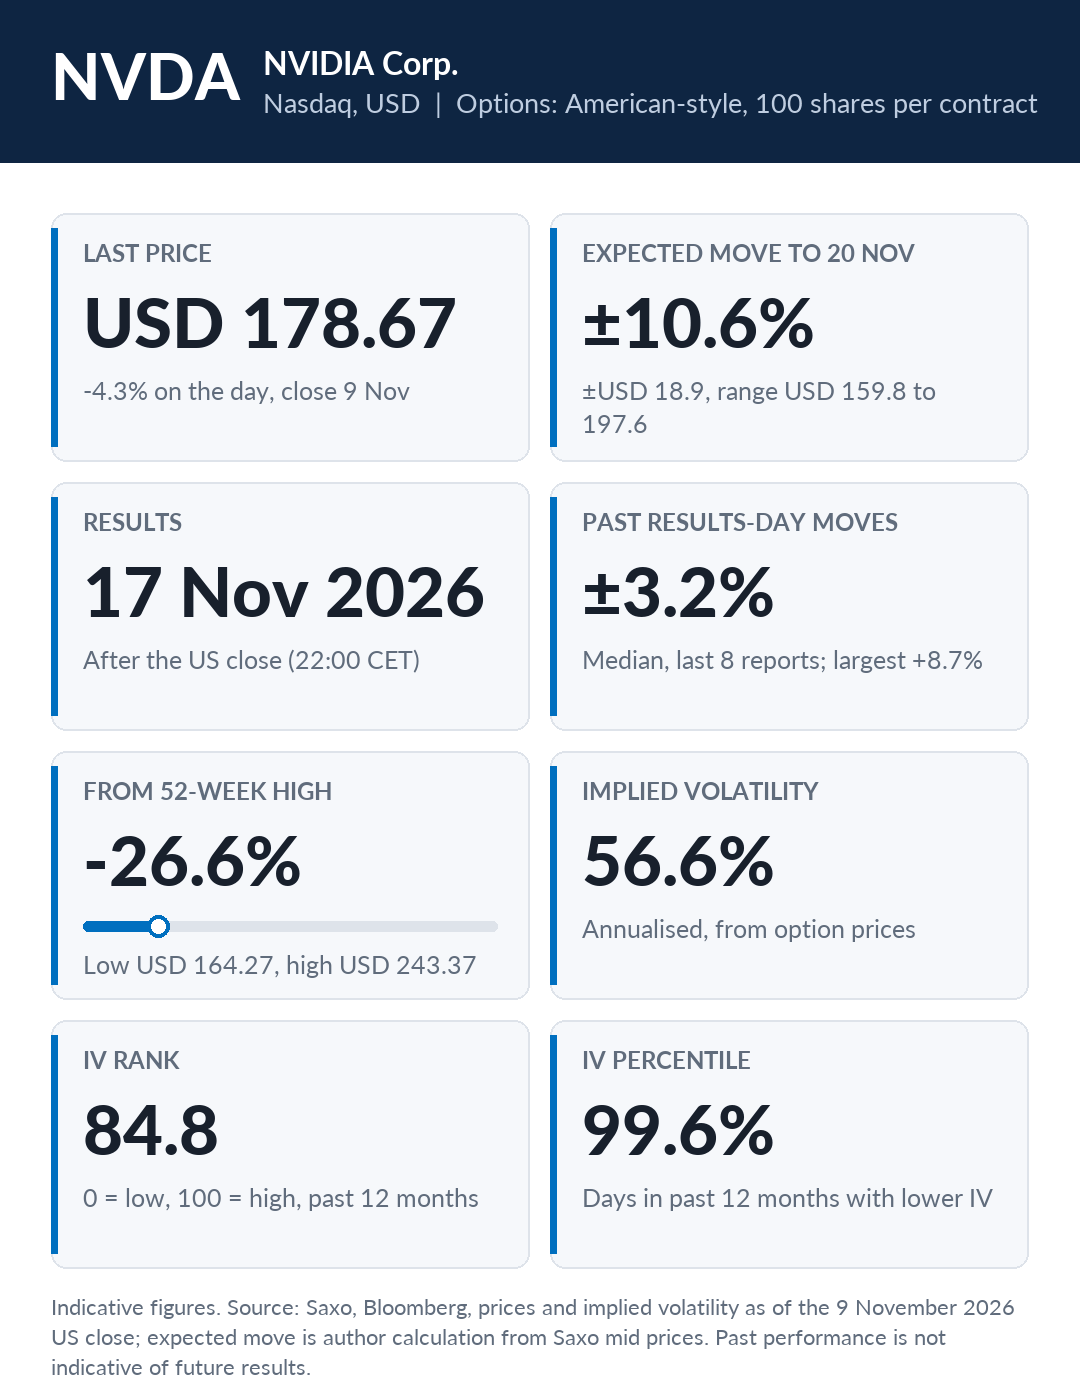 Key information on Nvidia. Indicative figures. Source: Saxo, Bloomberg, as of the 9 November 2026 US close. Past performance is not indicative of future results.
Nvidia has had two shocks in five days. On Thursday 5 November 2026 it fell about 9% in a broad sell-off in AI chip shares. On Monday 9 November it fell about 4% to USD 178.67 while most chip stocks rose, after CEO Jensen Huang admitted an affair with a woman who, according to press reports, US intelligence believes could be a Chinese spy. Independent directors are reviewing the matter, and the board says it has confidence in him. (Source: Saxo, as of 9 November 2026.) Past performance is not indicative of future results.
An investor who likes Nvidia faces two questions. One is demand and policy, which the report on Tuesday 17 November 2026, after the US close (22:00 CET), starts to answer. The other is Huang’s future, which it cannot settle, and analysts flag key-person risk. In our view the business itself appears unchanged by this news, but that is an opinion, and the shares could fall further or recover. Future outcomes are uncertain and may result in losses.
How a cash-secured put works
Selling a put means agreeing to buy 100 shares at a fixed price, the strike, if the stock is below it at expiry. The seller gets a premium now and keeps it either way. Cash-secured means the full price stays in the account: about USD 16,000 at a 160 strike.
The premium rises with implied volatility, the swing the market expects, and ahead of a report that swing is larger. Time decay, known as theta, erodes the option a little each day, which benefits the seller.
Adding the at-the-money call and put for 20 November 2026 gives a rough guide to the move being priced in: near USD 19, or about 11% either way. (Call USD 10.13 + put USD 8.78 at the 177.5 strike, about USD 18.90; indicative mid prices, Saxo, as of the 9 November 2026 US close.)
Important note: The strategies and examples provided in this article are purely for educational purposes. They are intended to assist in shaping your thought process and should not be replicated or implemented without careful consideration. Every investor or trader must conduct their own due diligence and take into account their unique financial situation, risk tolerance, and investment objectives before making any decisions. Remember, investing in the stock market carries risk, and it’s crucial to make informed decisions.
Route 1: selling a put before the report
The thesis: an investor happy to own Nvidia at a lower price receives a premium now for agreeing to buy at that price, and the premium is larger because the report is coming. Above the strike at expiry the investor keeps the premium and buys nothing. Below it, the investor buys 100 shares at the strike, even if the shares have gapped far lower. The premium cushions only part of that loss.
The first expiry after the report is Friday 20 November 2026, the standard monthly. Friday 18 December 2026 pays more but ties up cash longer.
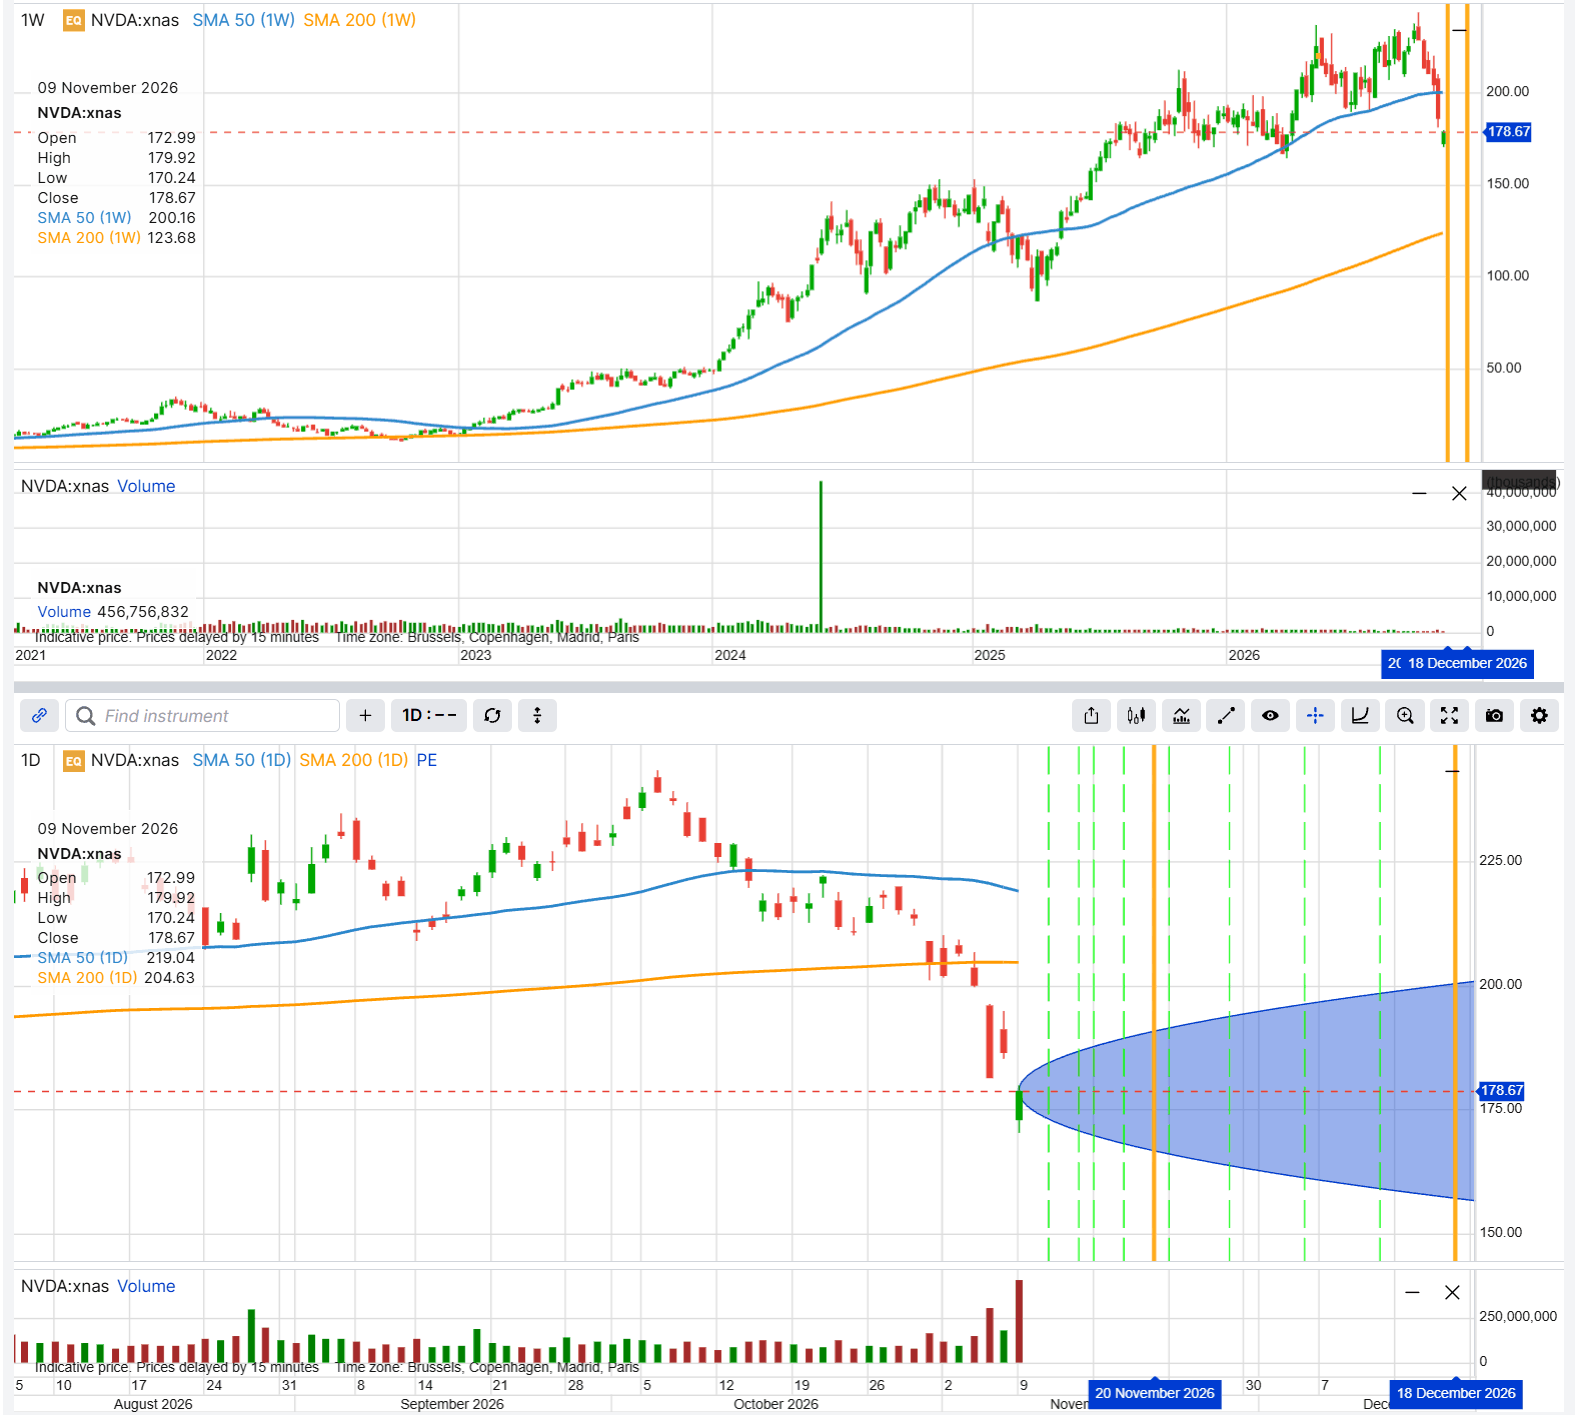 Nvidia weekly and daily chart, with the range implied by options prices out to 18 December 2026. Source: Saxo. Past performance is not indicative of future results. This chart is illustrative and for educational purposes only; it is not predictive.
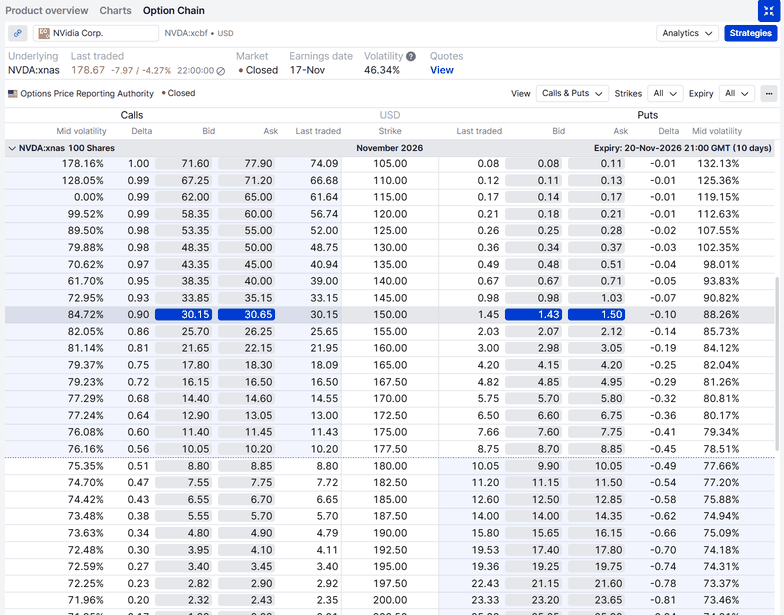
NVDA puts, 20 November 2026. Source: SaxoTraderPRO. Illustrative only. Past performance is not indicative of future results.
The following examples are hypothetical and for educational use only; they are not advice or trade recommendations.
Example structure (illustrative only - not a trade recommendation)
- Sell 1 NVDA 20 Nov 2026 160 put (limit price USD 3.00 per share, between the bid of 2.98 and the ask of 3.05)
- Premium received: USD 300 per contract
- Cash set aside: USD 16,000
- Break-even at expiry: USD 157.00, which is 12.1% below USD 178.67
- Maximum profit: USD 300, only if Nvidia closes at or above 160
- Maximum risk: USD 15,700, if Nvidia fell to zero and the investor bought at 160
- (Source: Saxo, indicative prices as of the 9 November 2026 US close, limit prices as entered in SaxoTraderPRO; author calculation)
This strategy carries substantial risk: below the strike the investor carries the full loss of owning the shares, and the premium offsets only a small part. Costs and charges apply to each leg and vary by account and venue; check the applicable rates before entering any position.
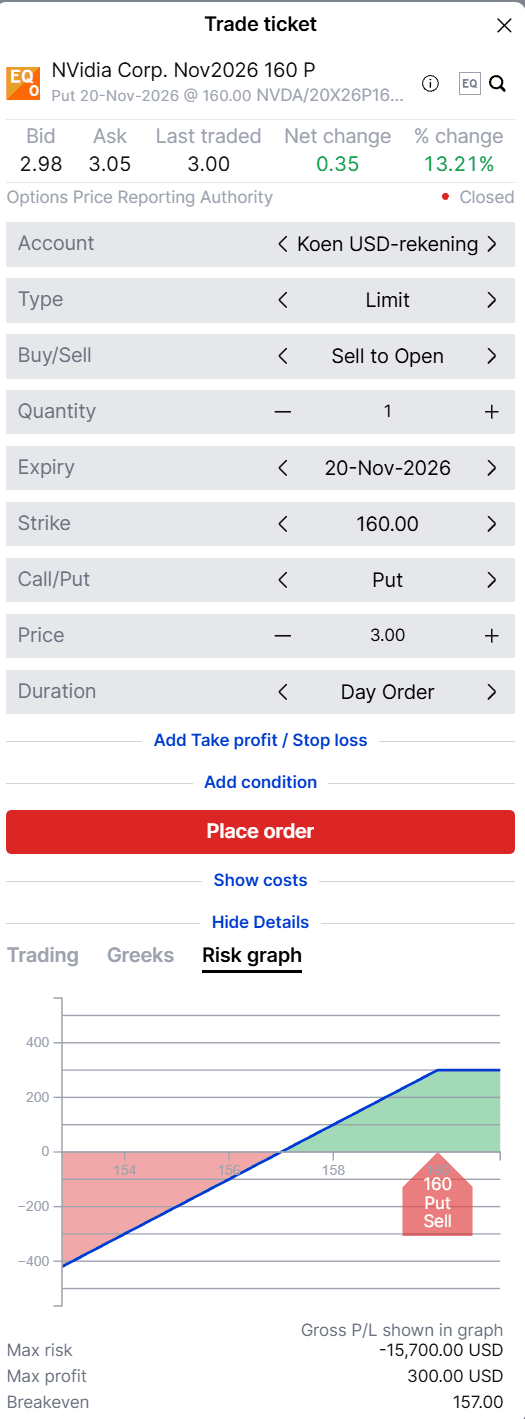
Risk graph for a short 160 put. Source: SaxoTraderPRO. This graph is illustrative and for educational purposes only; it is not predictive. Past performance is not indicative of future results.
The 18 December 2026 160 put pays about USD 5.50 per share (break-even near USD 154.50), but the shares have longer to fall. All premiums are indicative mid prices as of the 9 November close, not live quotes.
Strategy insight: the strike matters more than the premium. In this framework, the strike is a price the investor would be comfortable paying.
Route 2: selling a put after the report
The thesis: the same investor is happy to own Nvidia at a lower price but unwilling to bet on the report itself. Instead of selling today, the investor waits for the numbers and sells a put at the open on Wednesday 18 November 2026 (15:30 CET), with the result and the first reaction known.
Waiting buys two things. The first is protection from the report’s gap: a put sold today still obliges its seller to buy at the strike, even if the shares open far below it. The second is choice. If the shares fall after the report, the investor can pick a lower strike, nearer the new price; if they rise, a strike that still fits, or no put at all. Neither removes the obligation to buy at the strike if the shares fall below it after the put is sold.
The price of that choice is a smaller premium. Part of today’s premium exists only because the report is still ahead: the expiry that contains it carries far higher implied volatility than those around it, as the chart shows. Once the result is out, that extra usually drains away, a move known as IV crush. With the share price unchanged, the 18 December 160 put indicated at about USD 5.50 on 9 November would usually pay less on 18 November, and after a rally the strikes on offer sit further from where the investor wanted to buy.
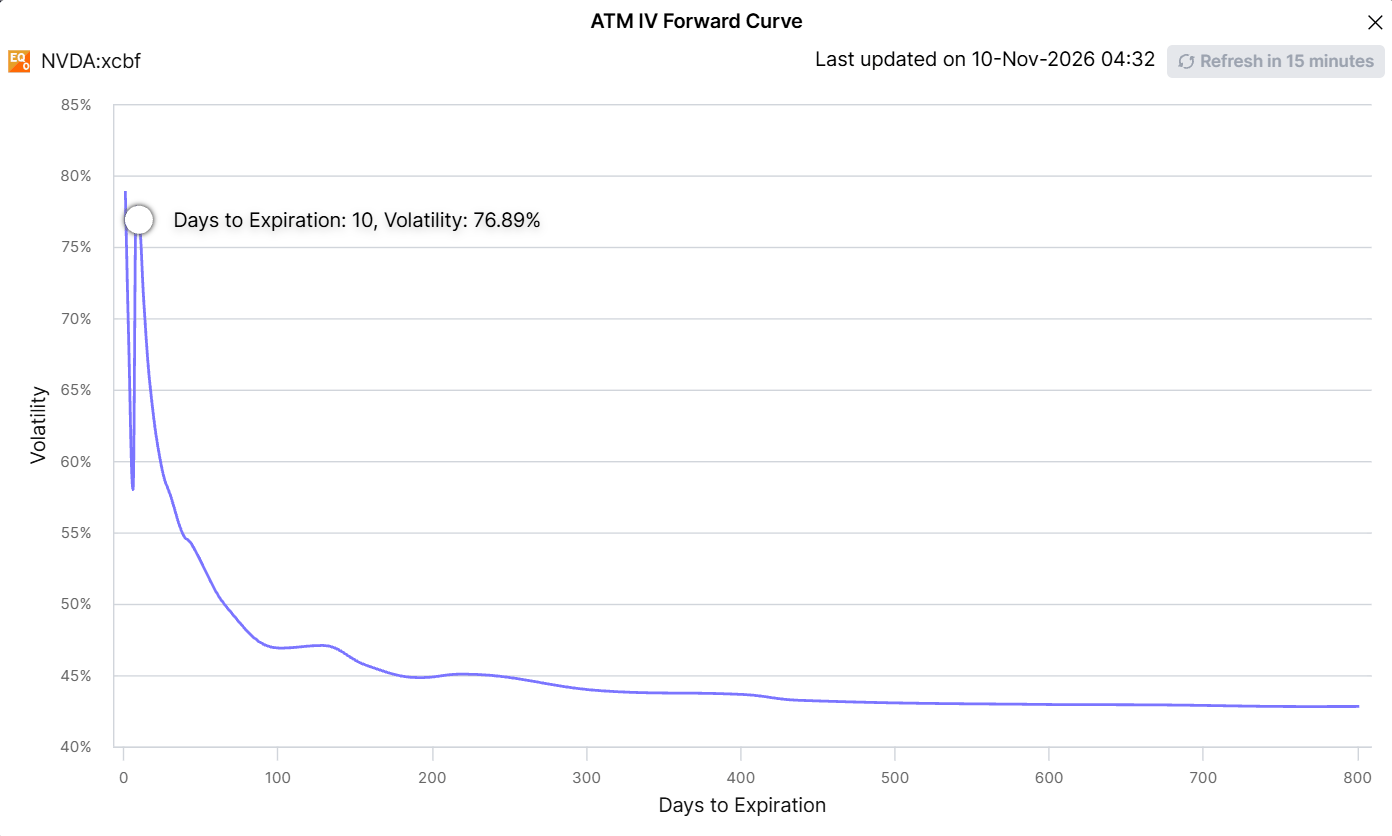 Nvidia at-the-money implied volatility by days to expiry, as of the 9 November 2026 US close. The spike is the expiry that contains the report. Source: SaxoTraderPRO. This chart is illustrative and for educational purposes only; it is not predictive. Past performance is not indicative of future results.
Waiting removes the report risk, but the Huang question remains. Three House committee chairs have asked Huang to attend a closed-door briefing on 18 November, the same day as this entry, and as of 7 November Nvidia had not said whether he would go (Source: Fox Business, as of 7 November 2026). The board review could also produce news at any time. Both routes carry the risk of owning the shares below the strike. Costs and charges apply and vary by account and venue; check the applicable rates before entering any position. Options carry a high risk of rapid loss and are not suitable for every investor.
Route 3: buying a put spread if the shares may fall further
Routes 1 and 2 suit an investor who wants to own Nvidia. Others hold the shares and fear a further fall. A put spread has a defined maximum loss and, if implied volatility is high, costs less than a single put. It combines a bought put at a higher strike, which gains if Nvidia falls, and a sold put at a lower strike, whose premium pays for part of the first. The gain stops at the lower strike, and if Nvidia stays flat or rises the whole cost is lost.
The following example is hypothetical and for educational use only; it is not advice or a trade recommendation.
Example structure (illustrative only - not a trade recommendation)
- Buy 1 NVDA 20 Nov 2026 170 put (mid about USD 5.75 per share)
- Sell 1 NVDA 20 Nov 2026 150 put (mid about USD 1.47 per share)
- Net debit: USD 5.75 minus USD 1.47 is about USD 4.28 at mid; the order ticket moves in 5-cent steps, so the example uses a USD 4.25 limit, USD 425 per contract
- Maximum profit: USD 20 minus USD 4.25 per share, USD 1,575 per contract, if Nvidia closes at or below 150
- Maximum risk: the net debit, USD 425, if Nvidia closes at or above 170
- Break-even at expiry: USD 170 minus USD 4.25, USD 165.75
- (Source: Saxo, indicative prices as of the 9 November 2026 US close, limit prices as entered in SaxoTraderPRO; author calculation)
This strategy carries a defined but real risk: the entire net debit can be lost if the shares do not fall, and the sold put carries assignment risk below 150. Costs and charges apply to each leg and vary by account and venue; check the applicable rates before entering any position.
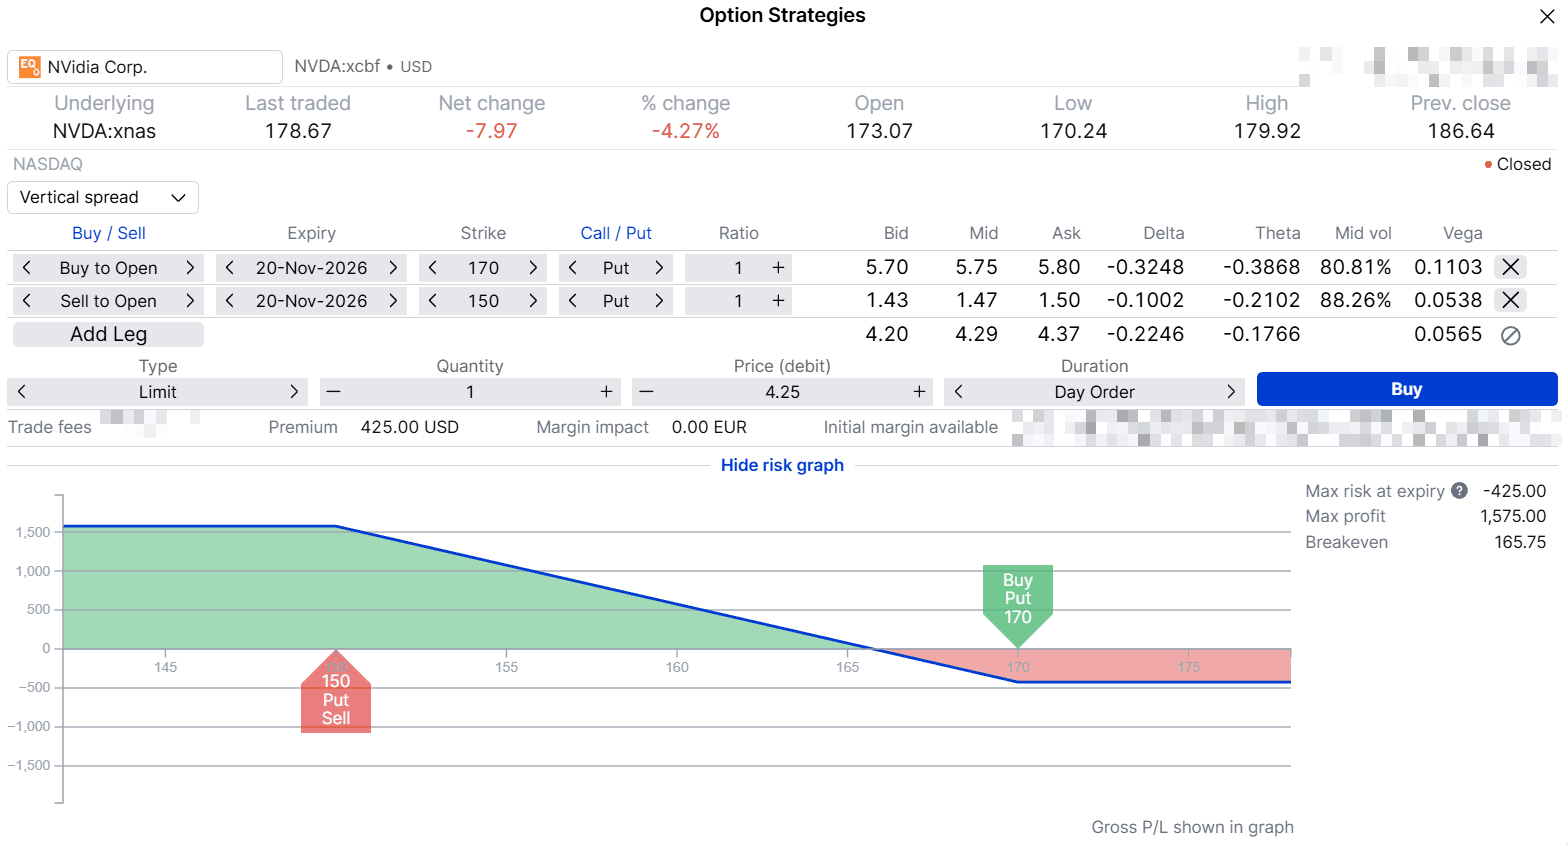 Risk graph for a put spread. Source: SaxoTraderPRO. This graph is illustrative and for educational purposes only; it is not predictive. Past performance is not indicative of future results.
If Nvidia closes at or above 170 at expiry, the whole debit is lost.
Points worth checking before any position:
- Bid/ask spreads and volume at each strike
- Cash for 100 shares, and whether owning them is acceptable if the CEO situation worsens
- For a spread, that the maximum loss is acceptable
- An exit plan: positions can often be closed before expiry
Assignment note: Nvidia options are American-style, so the seller of a put, including the sold leg of a spread, can be assigned before expiry, especially near expiry or ex-dividend dates. A buyer of an option faces no assignment risk.
Final thoughts
Options give an investor more than one way to act on a view. A put sold before the report pays more, one sold after it pays less with the result known, and a put spread caps the cost of a further fall. None removes risk, and doing nothing is also a choice. Options carry a high risk of rapid loss and are not suitable for every investor.
Two questions are open: the business, which the report may start to answer, and who leads it, which could take longer. A structure chosen for one and ignored for the other may not hold up.
The author does not hold positions in any of the instruments mentioned in this article and is permitted to wait at least 24 hours from the time of the publication before trading the instruments themselves.
| Related articles/content |
|---|
| Prune and plant after the storm what a sell-off changes for two option trades | 6 Nov 2026 Novo Nordisk results your shares are Danish the options are American | 29 Oct 2026 UBS reports on Wednesday two ways to name your price while Bern decides | 27 Oct 2026 Novartis results buying lower or selling higher when the big moves come from elsewhere | 23 Oct 2026 CoreWeave after the bond scare what a cash-secured put pays for and what it carries | 21 Oct 2026 Finding unusually expensive or cheap options in the Saxo screener | 18 Sep 2026 What IV crush really means in practice reviewed version | 9 April 2026 Trading earnings with defined | 31 Mar 2026 |
| More from the author |
|---|