
You can access both of our platforms from a single Saxo account.

Bonds take the hit, equity volatility eases - Options Brief - 11 November 2026
Summary: A hot inflation report sent bond volatility sharply higher, yet the price of index protection kept falling. Is the option market right to treat this as a bond story only?
A hotter inflation report sent Treasury yields and bond volatility sharply higher, while the price of index protection kept falling.
MARKET REGIME: NEUTRAL / CHOP | VIX 19.46 | TERM STRUCTURE: CONTANGO | SKEW: ELEVATED (151.12) | FRONT-MONTH VIX FUTURES: 19.200
Today in brief
Tuesday brought a third straight upside surprise on US inflation, and in our view the bond market took most of it. The two-year Treasury yield rose 17 basis points to 4.74% as markets moved to fully price a December rate hike. MOVE, a gauge of how much options expect Treasury yields to swing, rose 7.50% to 92.44. Stock options moved the other way. The one-day volatility gauge, which measures what options charge for protection over the next session, fell 19.41% to 13.95, and the VIX, the same measure over a month, eased 2.31% to 19.46.
The S&P 500 fell only 0.38% to 7,520.93. Today’s expiry prices a move of about 0.65%, on a day when the US bond market is closed. The 13 November expiry prices 1.21%, below the 1.29% that the passing of one session alone would have left from Tuesday’s reading. In our view the option market may be treating the inflation shock as a rates story rather than a stock story.
Nvidia is the exception, and it reports on 17 November. It fell 5.47%, and its volatility rank, which places today’s option prices within their range over the past year, rose to 95.9 from 84.9, while the S&P 500 fund’s rank eased. Activity in its options was heavy: about 7.3 million contracts traded on Tuesday, roughly 2.4 times the average of the previous 20 sessions, and open interest, the number of contracts still open, reached 16.9 million, the highest in our records since early July. Puts and calls were close to balanced, at 0.98 puts open for every call. Options price a move of about 8.3% for the report day alone, roughly twice the 4.0% the stock has moved on average after its last eight reports, and close to the largest move in that run, 8.7%.
SKEW, which tracks the price of protection against a very sharp fall, edged up 0.52% to 151.12. Both MOVE and the VIX still sit about a fifth above their medians in our store, so in our view neither market looks calm.
The index has used 82% of the week’s priced range. The typical single stock’s volatility rank eased to 37.3 from 39.4, and the flow carried no readable direction beyond protection bought on Nvidia.
That is the whole brief in one read. The sections below hold the detail behind each paragraph, with the charts, the full set of readings and the sources, for when you want to go deeper on one part.
Headline driver
US October consumer prices rose 0.4% on the month against 0.3% expected, and core prices 0.3% against 0.2%, according to the Saxo Market Quick Take. It is the third upside surprise in a row. Fed Governor Waller backed a December rate hike and said a larger move could be considered, and markets now fully price a December hike, with two more by next June.
Treasuries slumped: the two-year yield rose 17 basis points to 4.74%, and the ten-year yield briefly topped 5% and a ten-year note auction drew weak demand. The dollar rebounded and gold fell about 2%. Stocks gave up less: Nvidia fell 5.47%, Microsoft fell 2.2%, Broadcom rose 3.9%, and financials and energy held up. The Quick Take ties Nvidia’s fall to company-specific concerns. The US bond market is closed today for Veterans Day, while stocks trade.
Market snapshot
- US (Tuesday 10 November close): S&P 500 7,520.93, down 0.38%. Nasdaq 100 27,740.80, down 0.60%. The Dow Jones Industrial Average fell about 0.3%. The equal-weighted S&P 500 was flat, down 0.02%. The technology fund fell 1.15% and the semiconductor fund 0.78%, while financials rose 0.52% and energy 0.44%. The gold fund fell 2.68% and the gold miners fund 5.43%.
- Europe: the Stoxx 600 rose 0.27% to 658.32 and the DAX 0.31% to 26,347.45, with euro-zone banks up 1.68%. Euro Stoxx 50 futures traded 0.60% above their settlement at 05:00 CET.
- Asia (Wednesday morning): the Kospi rose 2.14% to 5,351.17 by 05:00 CET, while the Hang Seng fell 0.83%. The Quick Take has Taiwan’s Taiex up 3.6%, led by chipmakers.
- Commodities and rates: Brent traded at 92.51 and WTI at 86.62 at 05:00 CET. Gold futures traded at 4,054.0 and silver at 52.42. The two-year Treasury yield closed at 4.74% and the ten-year at 4.99%. S&P 500 futures traded 0.61% above their settlement.
- Market regime: neutral, the VIX at 19.46, the curve in contango and SKEW elevated at 151.12.
Index levels and volatility readings from the watchlist export taken at 05:00 CET on 11 November 2026, which carries Tuesday’s US closes and overnight futures; Treasury closes, the Taiex, the Dow move, single-stock moves and policy context from the same-morning Saxo Market Quick Take. Past performance is not indicative of future results. Source: Saxo, Bloomberg, CBOE.
Volatility surface
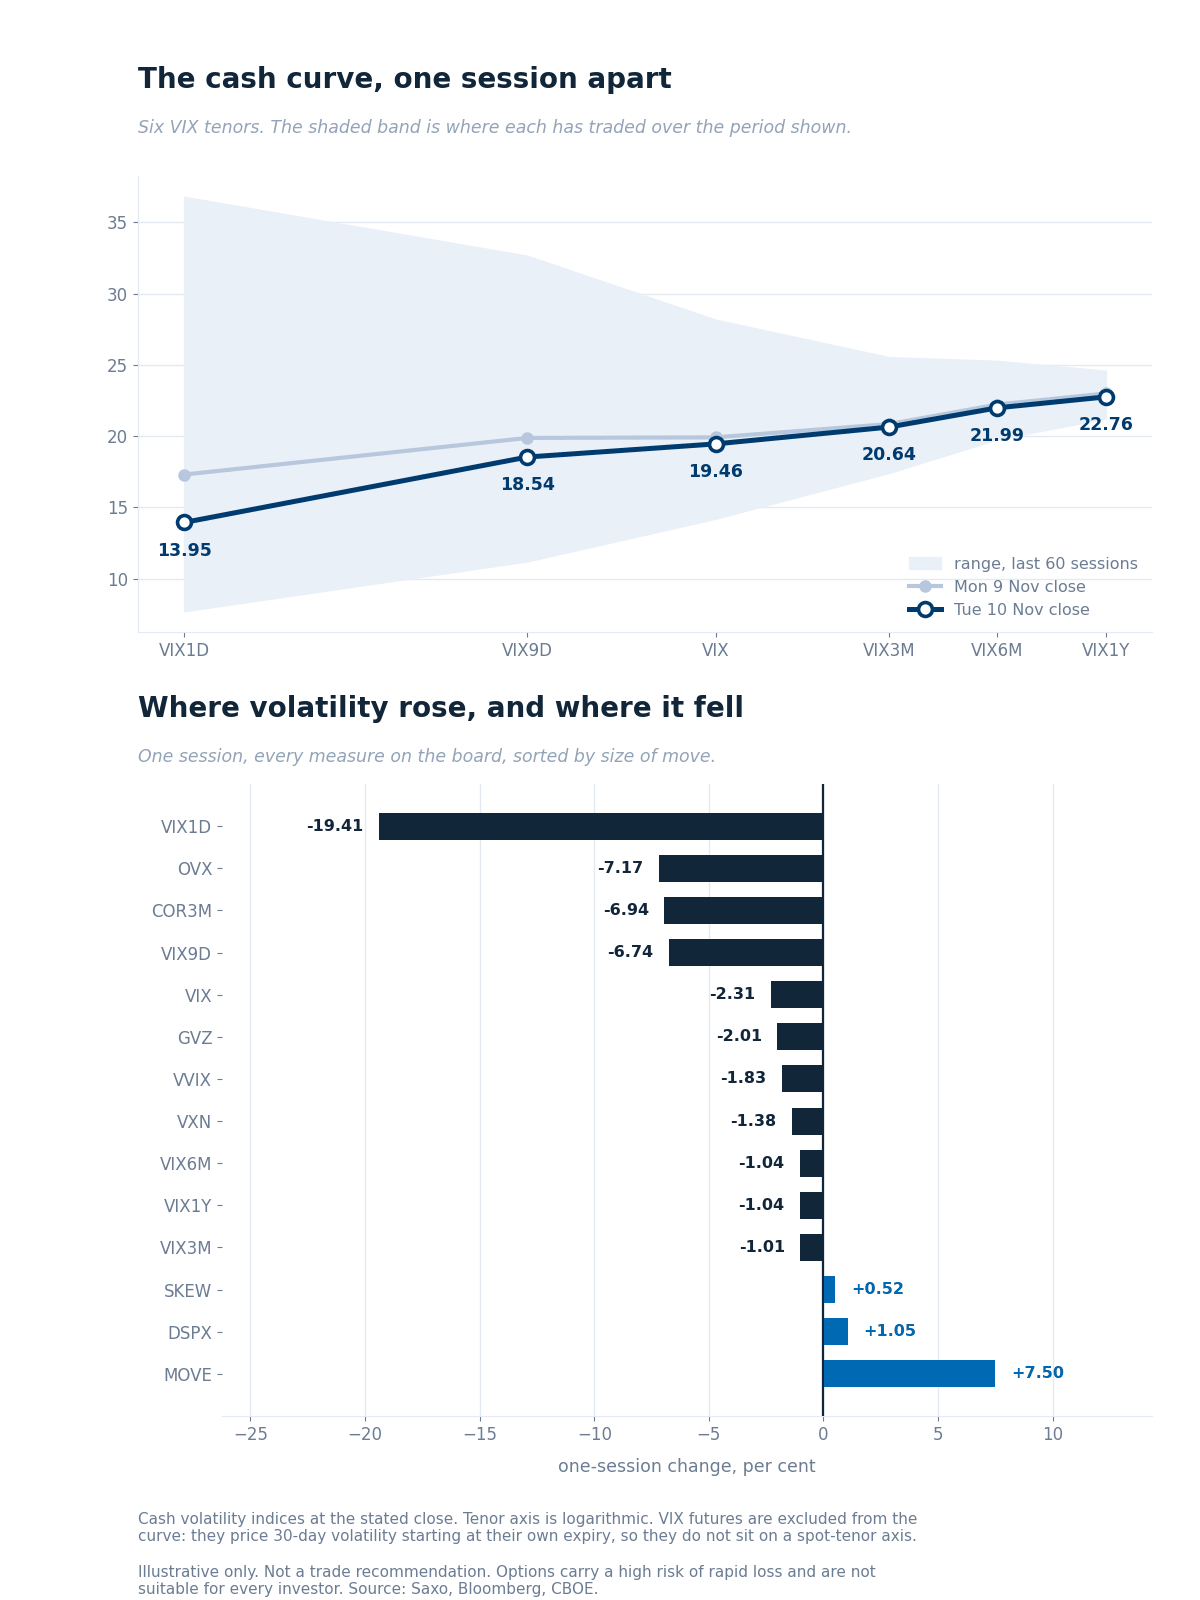
The cash curve at Tuesday’s close against Monday’s, over each tenor’s 60-session range, with the one-session change across every measure. Illustrative only. Past performance is not indicative of future results. Source: Saxo, Bloomberg, CBOE.
The front of the curve fell again and the rest barely moved. The one-day gauge fell 19.41% to 13.95 and the nine-day 6.74% to 18.54, while the three-month, six-month and one-year gauges each eased about 1%. MOVE was the largest riser on the board, up 7.50% to 92.44, against a median of 76.14 and readings near 100 in late October. The VIX at 19.46 sits against a median of 16.25, so both gauges remain about a fifth above their medians. VIX futures stay off the chart, since each prices a month from its own expiry.
Ratios. The one-day gauge sits at 0.72 times the VIX, from 0.87. VIX3M/VIX rose to 1.06 from 1.05, and VXN/VIX to 1.47 from 1.45: Nasdaq volatility still runs well above the broad gauge.
VIX futures. November trades at 19.20, 0.26 below spot, and December at 19.77, so the front contract now sits below the second. A parity check on the 18 November options, quoted from Tuesday’s close, reads 19.82; the future fell about 0.7 in overnight trade, so we draw no session comparison.
Tails and correlation. SKEW rose 0.52% to 151.12, above its 145.95 median. Implied correlation fell 6.94% to 13.81, against a 10.48 median.
Single-name volatility
Single-name volatility eased on the whole, though not in the US. On a common set of 521 underlyings the median implied-volatility rank fell to 37.3 from 39.4, and the mean to 39.6 from 41.1, with 336 names down and 176 up. Names at a rank of 80 or more rose to 28 from 25.
The split ran by region. The US median rose to 44.7 from 43.6, while the euro-zone median fell to 32.3 from 35.5.
The index measures above eased, but technology went the other way. The S&P 500 fund’s rank slipped to 31.3 from 32.4, while the Nasdaq 100 fund rose to 60.4 from 57.8 and the semiconductor fund to 66.3 from 59.7. Nvidia rose to 95.9 from 84.9, at the 99.6th percentile of its year, and Microsoft to 32.8 from 26.7. The long-dated Treasury fund rose to 43.7 from 40.2, and the two real-estate funds were among the largest risers, both up more than 12 points.
Implied-volatility rank and percentile from the Saxo screener, read early on 11 November 2026, carrying Tuesday’s close, against the reading carrying Monday’s close. Source: Saxo.
Options flow sentiment
Based on end-of-day Tuesday 10 November, yesterday’s positioning, not today’s price action.
- Single-name flow had no readable direction outside Nvidia, where the largest identifiable trades bought downside protection ahead of its report.
- Sector and ETF flow was unclear. Treasury, gold and defensive funds saw small, offsetting or paired trades, in our view too thin to confirm or contradict the move in rates.
Where the week's range sits
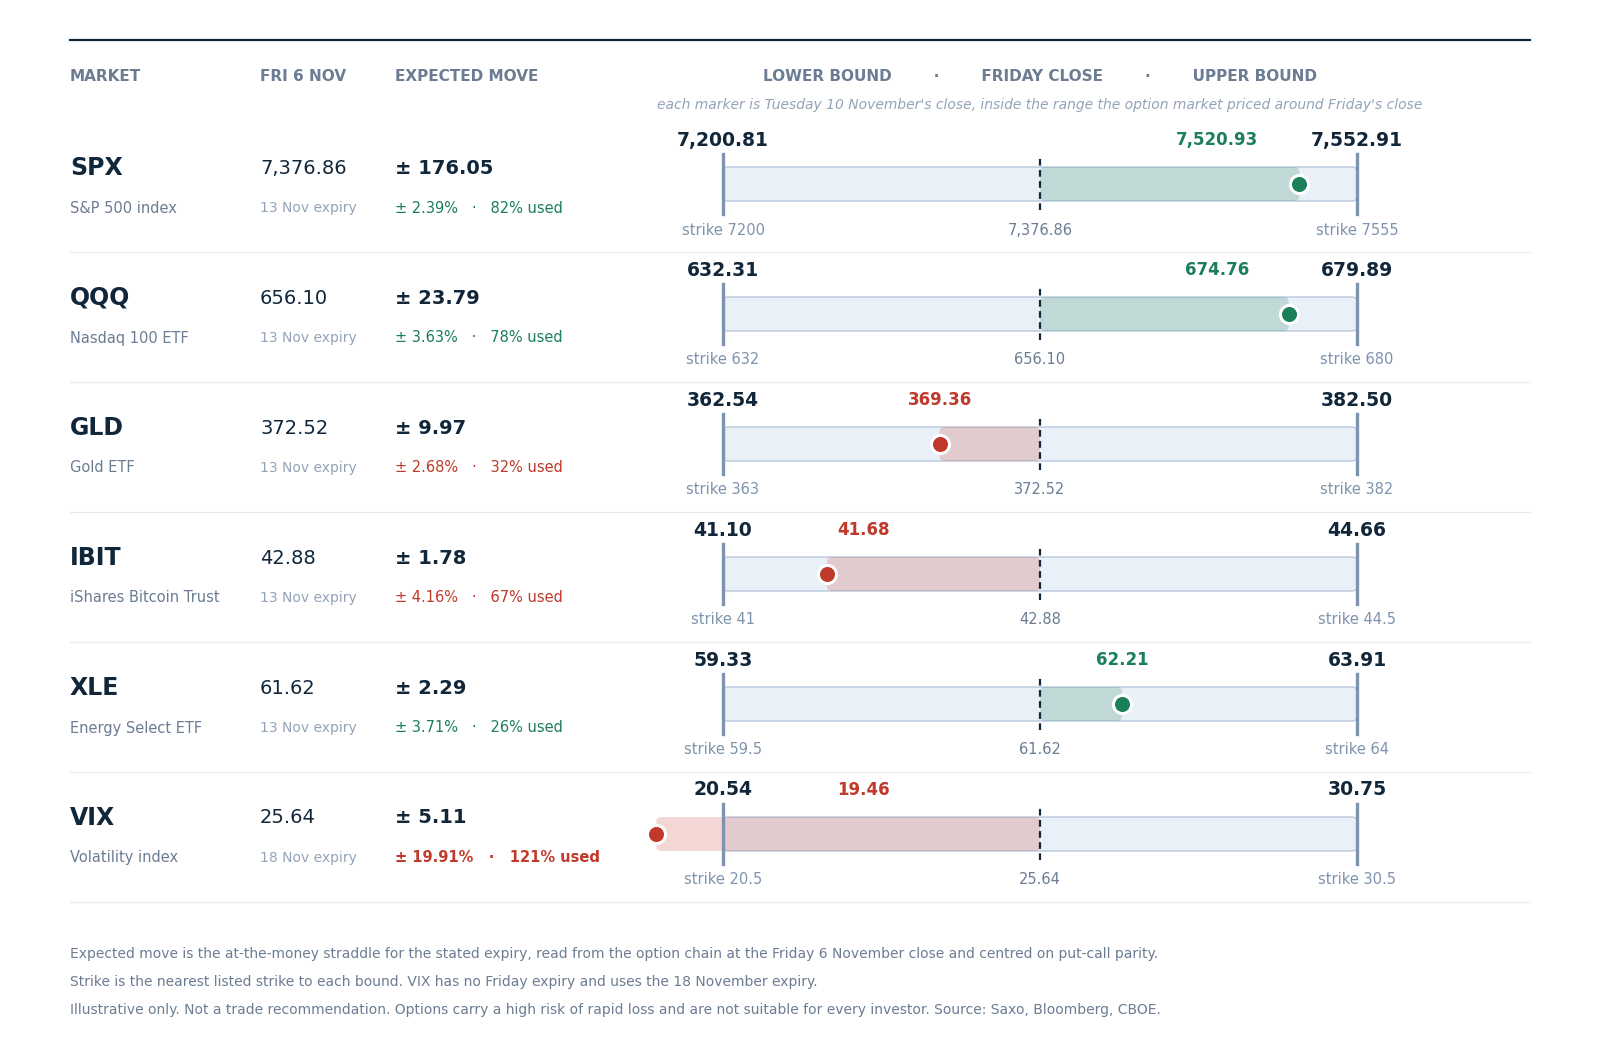
The range the option market priced for this week around Friday 6 November’s close, with each marker at Tuesday 10 November’s close. Illustrative only, not a trade recommendation. Past performance is not indicative of future results. Source: Saxo, Bloomberg, CBOE.
The S&P 500 started the week with 176.05 points, about 2.39%, priced around Friday’s 7,376.86 close, from 7,200.81 to 7,552.91. Tuesday’s close at 7,520.93 has used 82% of the range, down from 98% after Monday. The Nasdaq 100 fund has used 78%.
The VIX sits furthest outside its range. It closed at 19.46, below the 20.54 lower bound of its 18 November range, so it has used 121%. The bitcoin fund has used 67% to the downside, the gold fund 32% to the downside after Tuesday’s fall, and the energy fund 26%.
Options carry a high risk of rapid loss and are not suitable for every investor. Costs and charges apply and vary by account and venue; check the rates applicable to you.
Today's catalysts
- Today: the US bond market is closed for Veterans Day while US stocks trade; ECB President Lagarde speaks this morning; 13:00 CET US mortgage applications; OPEC’s monthly oil market report.
- Earnings today: Siemens Energy, E.ON and RWE.
- This week: US jobless claims, a 30-year bond auction and the delayed oil inventory report on Thursday, with Cisco and Applied Materials after the close; US October producer prices on Friday; Nvidia reports on 17 November.
Earnings scorecard
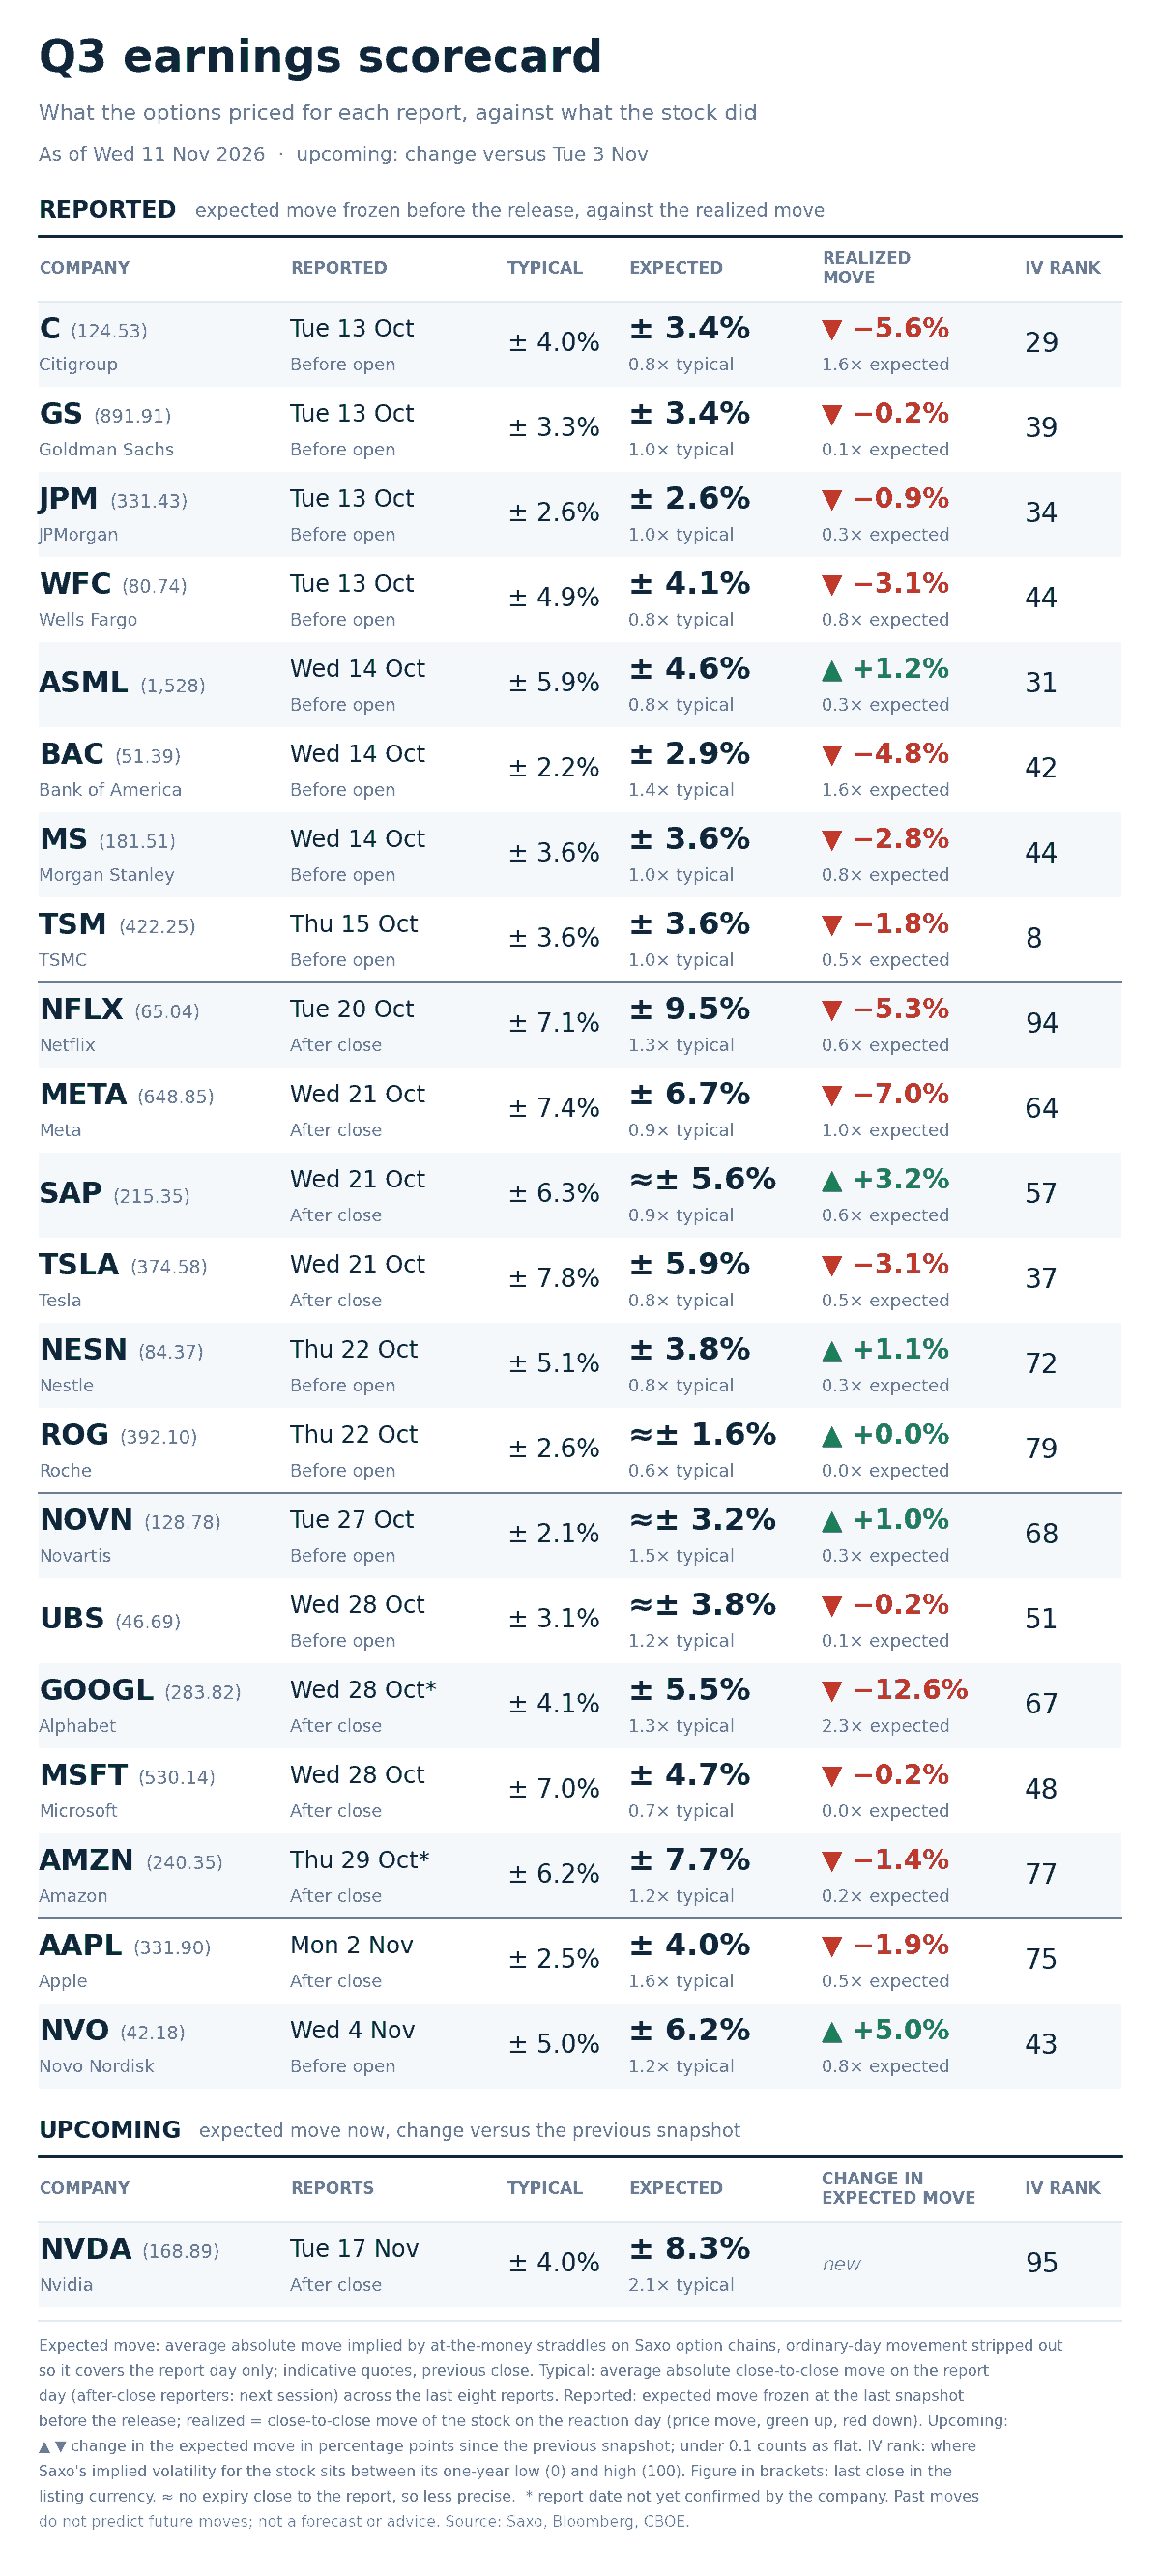
Option-implied expected move for each report day against the stock’s average move after its last eight reports, across the twenty-two names tracked this season. Past performance is not indicative of future results. Source: Saxo, Bloomberg, CBOE.
Nvidia joins the board as the one upcoming name. It reports on 17 November after the close, and options price an expected move of about 8.3% for the report day alone, 2.1 times the 4.0% it has moved on average after its last eight reports. That is close to the largest move in that run, 8.7% after the August report, and well above the median of 3.2%. The figure comes from indicative quotes before the open.
Interest in the stock’s options is running high into the report. About 7.3 million contracts traded on Tuesday, roughly 2.4 times the average of the previous 20 sessions, and open interest, the number of contracts still open, reached 16.9 million, the highest in our records since early July. Puts open stood at 0.98 per call and Tuesday’s trading at 0.85 puts per call, in our view a slight lean toward calls by count rather than a one-sided bet.
The other twenty-one names have reported, and their board is unchanged since Friday. Across that set the median moved about 0.5 times what was priced, and four moved at least as much as priced: Citigroup, Bank of America, Meta and Alphabet.
Options carry a high risk of rapid loss and are not suitable for every investor. Costs and charges apply and vary by account and venue; check the rates applicable to you. Past performance is not indicative of future results.
What the market is pricing
- Session implied range: S&P 500 options price about 49 points, 0.65%, for today’s expiry, on a day with the US bond market closed. The quotes are indicative before the open. The one-day gauge at 13.95 implies about 0.88%, a one-standard-deviation figure, a different measure from the expected move above.
- Week ahead: the 13 November expiry prices about 91 points, 1.21%. Tuesday’s edition quoted 112.65 points, 1.49%, for the same expiry from the same chain. Time alone would have left about 97.6 points, 1.29%, so in our view implied volatility itself came down. Netting out today leaves about 1.02% for Thursday and Friday, roughly 0.72% a session, a little above today.
- Rates against stocks: MOVE rose 7.50% on a day the VIX fell 2.31%. In our view that may suggest the market sees the inflation surprise mainly as a question for bonds and the Fed path.
- Tail read: SKEW edged up and Nvidia’s volatility rank climbed to 95.9 as the index fund’s eased. In our view that may suggest hedges are being kept on the tail and on single names rather than on the index as a whole.
In our view the next test may be Friday’s producer price report, which arrives with stock volatility near its lows of the week and bond volatility back on the rise. Options carry a high risk of rapid loss and are not suitable for every investor. Costs and charges apply and vary by account and venue; check the rates applicable to you. Past performance is not indicative of future results.
| More from the author |
|---|